Mortgage Pre-Approval Time in Tennessee
Mortgages, Tennessee Home Buying, Pre-Approval Timeline
Mortgage Pre-Approval Time in Tennessee: What Buyers Should Really Expect
“Most Tennessee buyers get pre-approved the same day or within 24 hours when they have their documents ready.” If you’re thinking about buying a home in Knoxville, Maryville, or anywhere in East Tennessee, that’s the kind of clear answer you’re probably looking for. Let’s unpack what that really means for you, what can speed things up, and what can slow things down.
What Really Affects Mortgage Pre-Approval Time in Tennessee?
Most lenders in Tennessee follow similar timelines to the rest of the country: many can issue a pre-approval within 1–3 business days when everything is straightforward and your paperwork is complete, and sometimes even the same day for well-qualified, W‑2 borrowers with simple finances, according to major national lenders and housing guides (Chase, Redfin). But there are three big factors that really determine how fast your pre-approval moves:
1. Lender Type and Technology
Some lenders still do almost everything by hand. Others use secure online portals and automated underwriting tools that can review your information quickly. Lenders using modern systems can often issue conditional pre-approvals much faster, especially for borrowers with straightforward income and credit. That’s one reason working with a local loan officer who knows East Tennessee and has access to efficient systems can really help your timeline.
2. How Ready Your Documents Are
In almost every delay story, there’s one common theme: missing paperwork. When you upload everything the lender needs up front, your file can often move through review the same day or within 24 hours. When documents are missing, outdated, or hard to read, the process slows down while your loan officer tracks things down with you.
3. How Complex Your Credit and Income Are
If you’re a W‑2 salaried employee with a steady job and clean credit, you’re usually on the faster side of the timeline. If you’re self-employed, work multiple jobs, recently changed careers, or have credit challenges, expect a little more time. National data shows that complex files can take 3–7 business days for pre-approval because underwriters may need extra documentation or explanations (Redfin, regional Tennessee guides).
Exact Documents You Need for Mortgage Pre-Approval in Tennessee
Here’s the short list you’ll want to gather before you apply. Having these ready is the difference between “same day” and “we’re still waiting on that document”:
- Government-issued photo ID – Driver’s license or passport.
- Recent pay stubs – Typically covering the last 30 days of income.
- W‑2s – For the past two years, if you’re a W‑2 employee.
- Tax returns – Often two years of full returns, especially if you’re self-employed or have side income.
- Bank statements – Recent statements for checking, savings, and other asset accounts (usually the latest 1–2 months).
- Statements for other assets – Retirement accounts, investments, or other funds you’ll use for down payment or closing costs.
- Debt information – Statements for car loans, student loans, and credit cards, if not easily visible on your credit report.
- Divorce or child support paperwork (if applicable) – Court orders or agreements that affect your income or obligations.
Different lenders may ask for slight variations, but this list covers what most Tennessee lenders want to see for a solid pre-approval decision (Investopedia, Bankrate, NerdWallet).
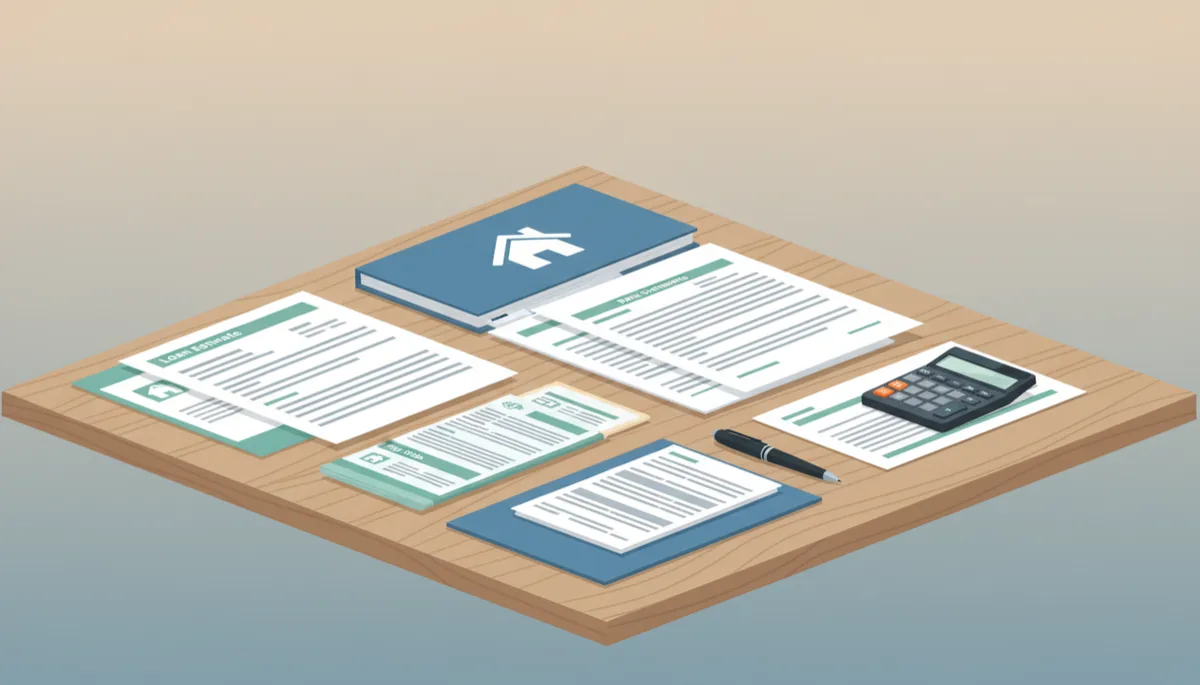
Having every document ready is the easiest way to speed up pre-approval.
Same-Day vs. 24-Hour vs. 3–5 Day Pre-Approval: What’s the Difference?
Same-Day Pre-Approval (Fastest Scenario)
Same-day decisions usually happen when:
- You’re a W‑2 employee with steady income and a consistent job history.
- Your credit history is relatively clean and easy to read.
- You upload every required document at once and respond quickly to questions.
In these cases, automated underwriting tools and an experienced loan officer can often review your file and issue a conditional pre-approval the same day, especially if you apply early in the day and the lender isn’t overwhelmed with volume.
Within 24 Hours (Very Common in Tennessee)
Many East Tennessee buyers fall into this bucket. Maybe your documents are mostly ready but the lender needs a few clarifications, or your file is being reviewed by a human underwriter after the initial automated pass. When your income and credit are straightforward and your paperwork is complete, 24 hours is a very realistic expectation with many lenders in the region.
3–5 Business Days (More Complex Situations)
A 3–5 day timeline is more typical when:
- You’re self-employed or own a small business and your income varies.
- You work multiple jobs or earn commissions, bonuses, or seasonal income.
- There are credit issues, past late payments, or items that need letters of explanation.
- It’s a busy time in the market and your lender is handling a high volume of applications.
In these cases, underwriters may need to dig deeper into your tax returns, business statements, or credit report, which naturally takes more time.
Pre-Qualification vs. Pre-Approval: Why the Difference Matters
These two terms sound similar, but in a competitive East Tennessee market, they’re not treated the same by sellers and listing agents.
Pre-Qualification
A pre-qualification is usually a quick estimate based on the information you tell the lender—sometimes without verifying documents. It can be helpful early on to get a rough idea of what you might afford, but it doesn’t carry much weight when you’re making an offer. Think of it as a conversation, not a commitment from the lender.
Pre-Approval
A pre-approval goes several steps further. The lender reviews your credit, income, assets, and debts using actual documentation and issues a letter stating that, based on what they’ve reviewed so far, you meet guidelines for a specific loan amount and program (subject to final underwriting and property approval). This is what listing agents in Knoxville, Maryville, and the surrounding areas want to see with your offer.
Common Pre-Approval Delays (and How to Avoid Them)
Even with the best intentions, a few common issues can slow things down. The good news: most of them are preventable if you know what to expect.
- Incomplete or missing documents: If your bank statements cut off pages, your pay stubs are out of date, or your tax returns are missing schedules, your lender has to circle back and ask for more. Double-check that everything is complete and legible before you upload it.
- Unexplained large deposits: If your bank statement shows a large deposit that doesn’t match your regular income, the underwriter may need a paper trail. Be ready with documentation (for example, a gift letter or proof of funds transfer).
- Credit report surprises: Collections, late payments, or errors on your credit report can slow things down while you and your loan officer sort out what’s accurate and what needs explaining. Checking your credit early in the process can help you spot issues before you’re under time pressure.
- Slow responses to lender questions: When your lender emails or calls asking for one more document, every day you wait to respond stretches out the timeline. Try to respond within the same day whenever possible.
Why Getting Pre-Approved Before House Hunting Matters in East Tennessee
In many East Tennessee neighborhoods, from West Knoxville to Maryville and surrounding communities, good homes still move quickly. When a well-priced home hits the market, it’s common for sellers to get multiple offers within the first few days. In that environment, showing up without a strong pre-approval is a real disadvantage.
- You know your budget before you fall in love with a house. Pre-approval helps you focus only on homes that fit comfortably within the range your lender says is realistic based on your finances.
- Your offer looks stronger to sellers. A local pre-approval letter signals that a lender has reviewed your credit, income, and assets—not just taken your word for it. Listing agents in East Tennessee often encourage sellers to favor fully pre-approved buyers.
- You can move quickly when the right home appears. If you wait to start pre-approval until after you’ve found a home, you may lose valuable days while other buyers are already writing offers.
Getting pre-approved first doesn’t obligate you to buy right away, but it does put you in a position to act confidently when the timing is right.
Ready to Get Pre-Approved with a Local East Tennessee Loan Officer?
If you’re buying in Knoxville, Maryville, or anywhere in East Tennessee, working with a local loan officer who understands the market, local appraisers, and typical contract timelines can make the process smoother and less stressful.
Jeff Morgan with Equity Smart Home Loans is based in Maryville, TN and focuses on helping Tennessee buyers understand their options clearly and move through pre-approval efficiently—without pressure or confusing jargon. Whether you’re a first-time buyer or you’ve bought homes before, you’ll get straightforward guidance on what to expect and what you can do to keep your timeline on track.
Two Easy Ways to Get Started Today
- Book a quick call with Jeff: Have questions about your specific situation, credit, or income? Schedule a no-obligation, 10‑minute conversation and get your questions answered before you apply: Book a call with Jeff.
- Start your online application: If you’re ready to begin the pre-approval process now, you can securely upload your documents and start your application here: Start your loan application.
With your documents ready and a clear understanding of the process, most Tennessee buyers can move from “thinking about it” to fully pre-approved in a surprisingly short time—often the same day or within 24 hours. From there, you and your real estate agent can shop for homes in East Tennessee with confidence, knowing exactly where you stand.
If you’re even thinking about buying in the next few months, getting pre-approved now is one of the smartest, lowest-stress steps you can take. It doesn’t lock you into a specific property, but it does give you clarity, confidence, and a stronger position when the right home comes along.
Jeff Morgan | NMLS #2737554 | Equity Smart Home Loans | NMLS #856170 | Equal Housing Lender | equitysmartloans.com | Rates, fees and programs are subject to change without notice. All applications subject to underwriting guidelines and approval. This does not constitute an offer to lend.